Tactical Capital, Institutional Discipline
Four institutional mandates engineered to capture asymmetric yield — from build-to-core BTR development and multifamily value-add to corporate build-to-suit and investment-grade net lease acquisitions.
Texas BTR Development
Build-to-Core — Institutional Growth via Vertical Integration
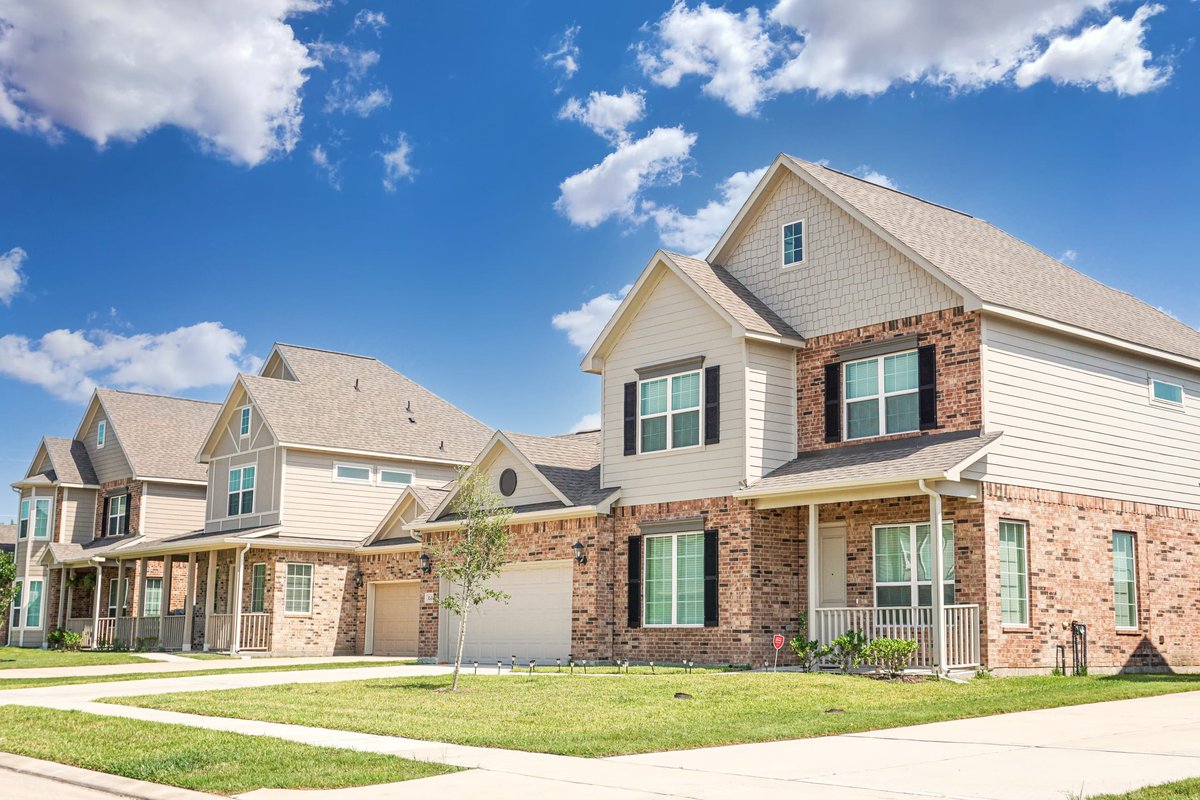
By anchoring to a captive land bank, we neutralize execution risk and secure outsized institutional development margins.
We systematically deploy cross-border capital to manufacture institutional-grade BTR communities, activating the Group’s proprietary 16,000-unit future land pipeline.
Proprietary Sourcing & Immediate Deployment
Direct, off-market access to a strictly vetted $610M actionable pipeline, bypassing competitive market bidding to ensure immediate capital efficiency and yield generation.
Asymmetric Risk Mitigation
Structured programmatic JVs leverage Wan Bridge’s captive construction infrastructure and the AiWB enterprise system to establish fixed construction costs, compress delivery schedules, and structurally de-risk ground-up development.
Multifamily Value-Add & Special Situations
Multi-Lever Execution — Distress & Regulatory Arbitrage
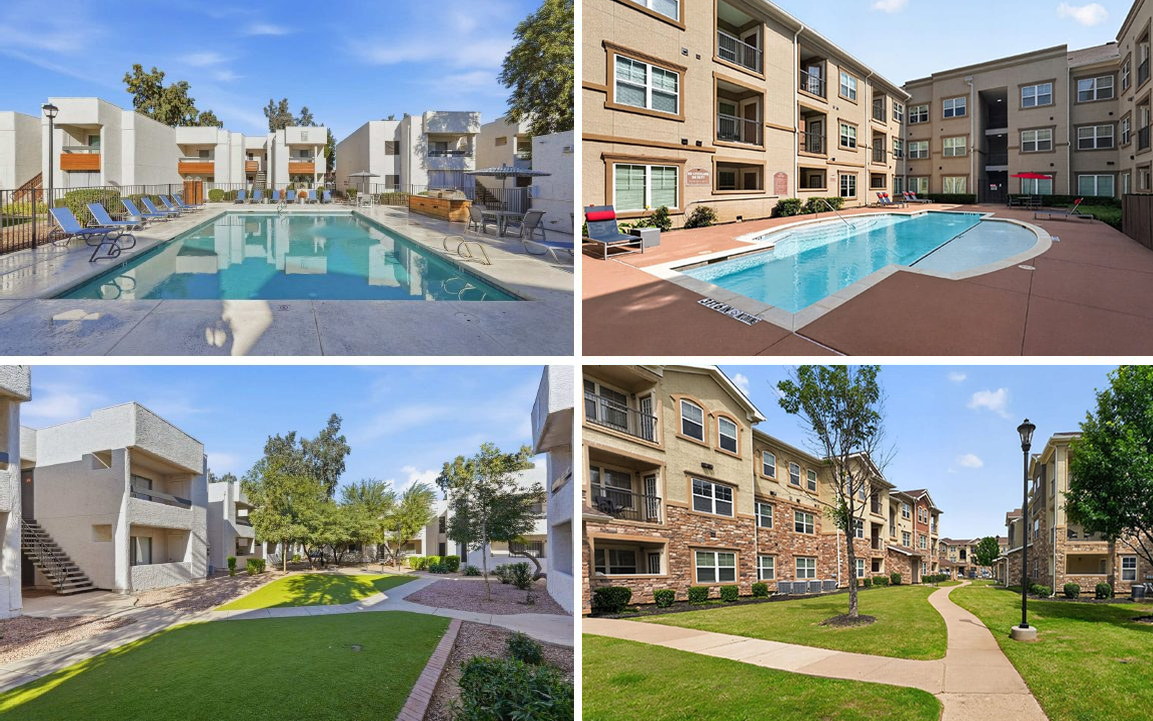
Distress is the entry point, not the investment thesis. Impaired capital structures combined with operational repositioning and regulatory arbitrage establish a permanent valuation floor.
We target relative-value dislocations across U.S. growth markets, acquiring structurally impaired but fundamentally sound multifamily assets. By deploying a multi-lever execution strategy, we force asset appreciation independent of broader market beta.
Capital Stack Recapitalization
Deploying rescue capital to recapitalize over-leveraged debt profiles at a 25%–50% discount to replacement cost, resolving immediate liquidity shortfalls and resetting the cost basis.
Physical Repositioning
Executing highly targeted CapEx programs on acquired distressed assets to upgrade asset classifications, capturing immediate mark-to-market rent premiums in supply-constrained submarkets.
Affordable Housing Conversion
Leveraging structural government incentives to convert standard assets into Affordable Housing classifications. Securing comprehensive tax abatements to drive a 20%–35% NOI expansion independent of rent growth.
Corporate Build-to-Suit (BTS) Development
Yield-on-Cost Arbitrage & Mission-Critical Infrastructure
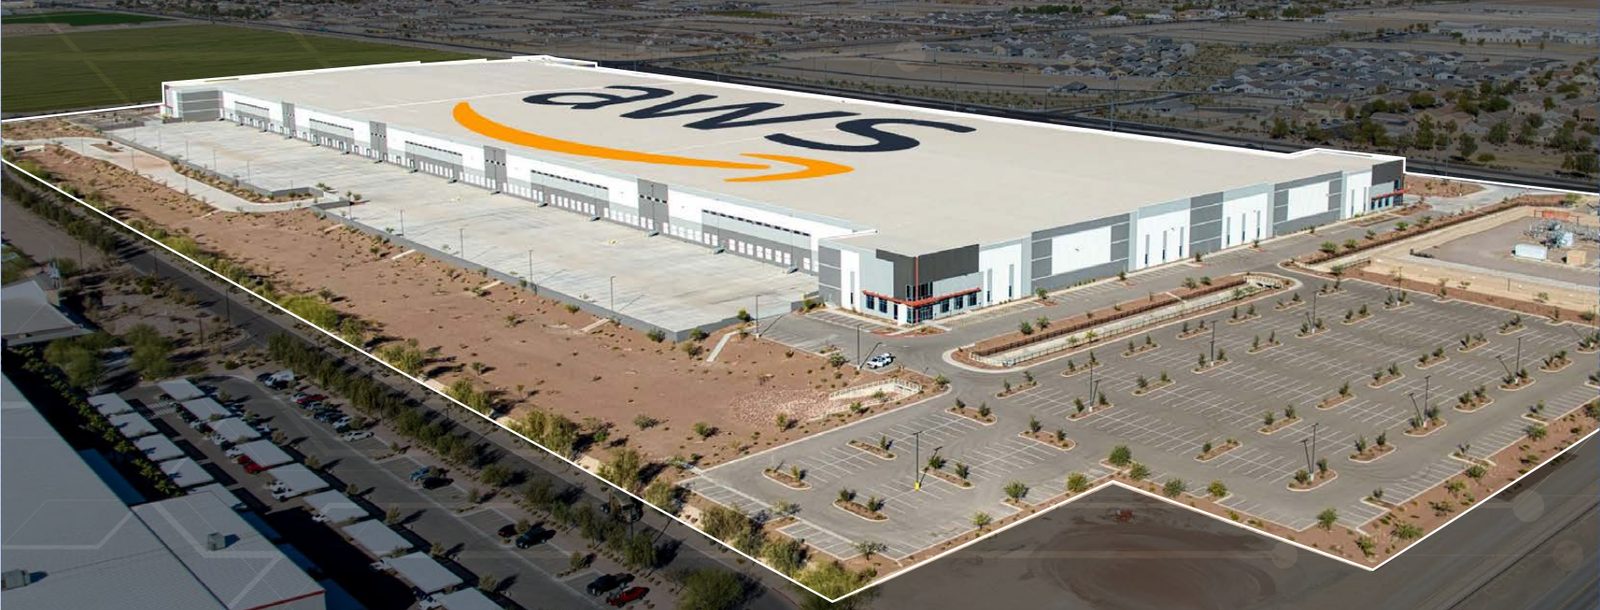
Manufacturing core assets through dedicated corporate partnerships allows us to lock in investment-grade credit prior to capital deployment, effectively underwriting the exit at inception.
We structure customized forward-funding and development mandates to capture outsized margins through investment-grade (IG) corporate tenancy. By executing ground-up build-to-suit projects, we manufacture premium institutional products at a structurally lower basis.
Forward Funding & BTS Development
Delivering tailored, ground-up build-to-suit projects for mission-critical facilities — spanning EV infrastructure, advanced logistics, and corporate headquarters — backed by Fortune 500 and IG tenants.
Development Alpha
Leveraging proprietary origination to generate significant Yield-on-Cost (YoC) spreads, capturing pure development arbitrage prior to stabilization and institutional exit.
Institutional STNL Acquisitions
Credit Arbitrage & Defensive Capital Preservation
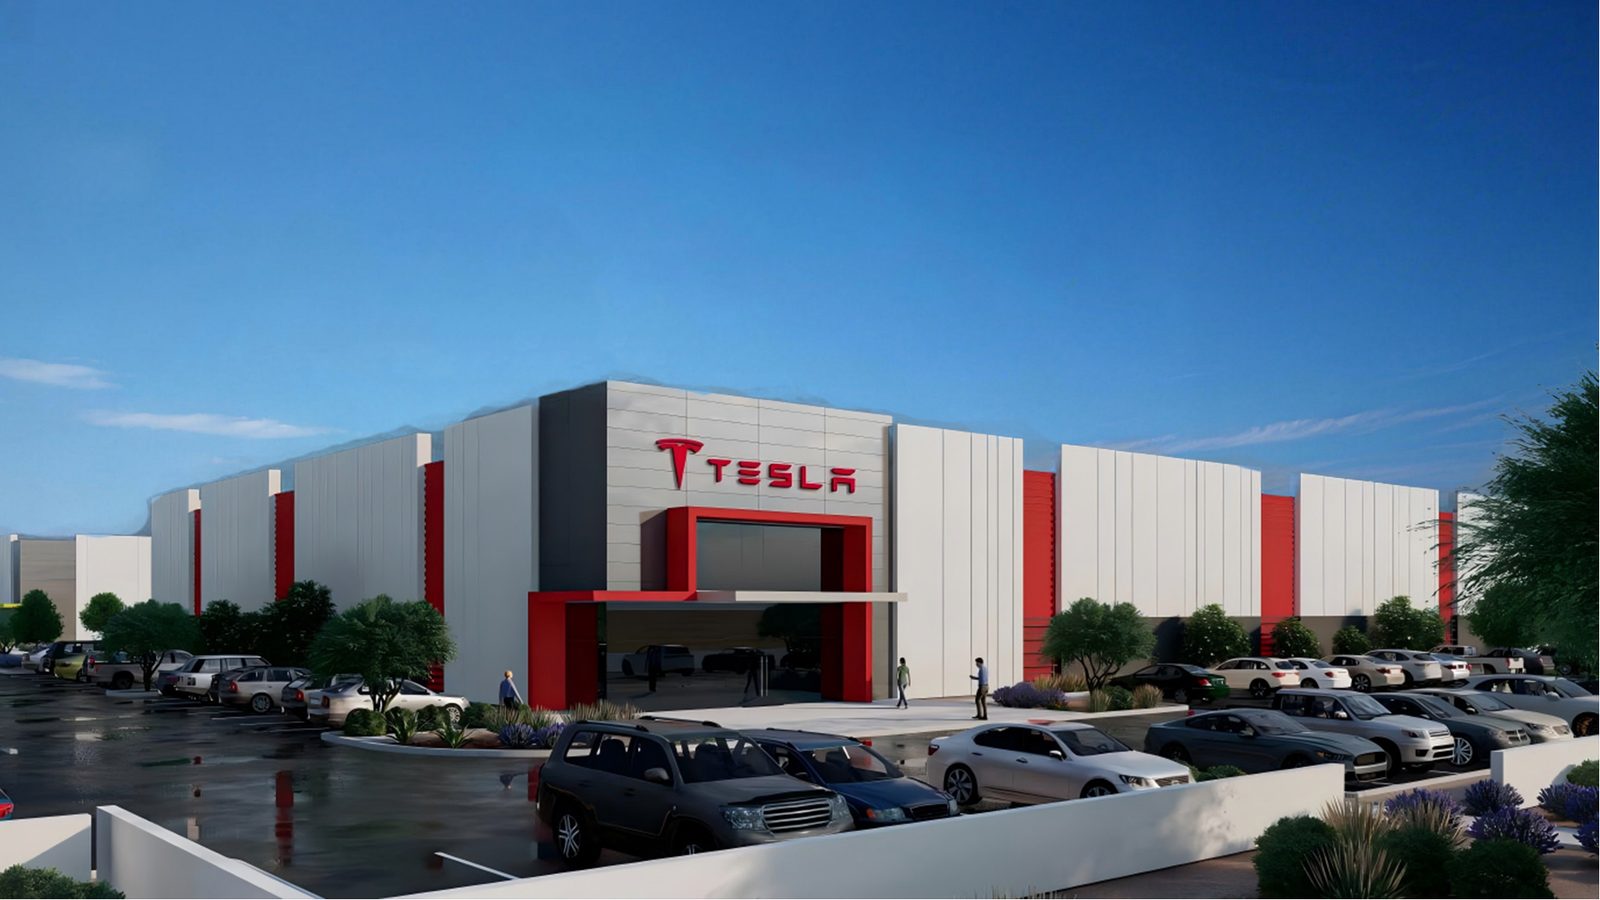
NNN assets backed by investment-grade credit act as the ultimate portfolio stabilizer. We are fundamentally acquiring corporate bonds wrapped in real estate, offering durable cash yields with absolute downside protection.
We opportunistically acquire stabilized, mission-critical assets backed by long-term NNN leases. This strategy anchors the portfolio with investment-grade credit, providing a highly defensive foundation of inflation-protected cash flows.
Investment-Grade Tenancy
Acquiring single-tenant net lease (STNL) properties occupied by Fortune 500 and globally recognized corporate entities (e.g., Tesla, Amazon). We strictly underwrite corporate guarantor strength, unit-level profitability, and underlying asset fungibility.
Bond-Proxy Cash Flow
Delivering defensive, compounding current yield through 15-year+ net leases with fixed annual escalations. Zero landlord CapEx leakage effectively insulates deployed capital from macroeconomic volatility and operational inflation.
Multi-Tenant Retail Acquisitions
100% NNN Execution on Irreplaceable Retail Corridors
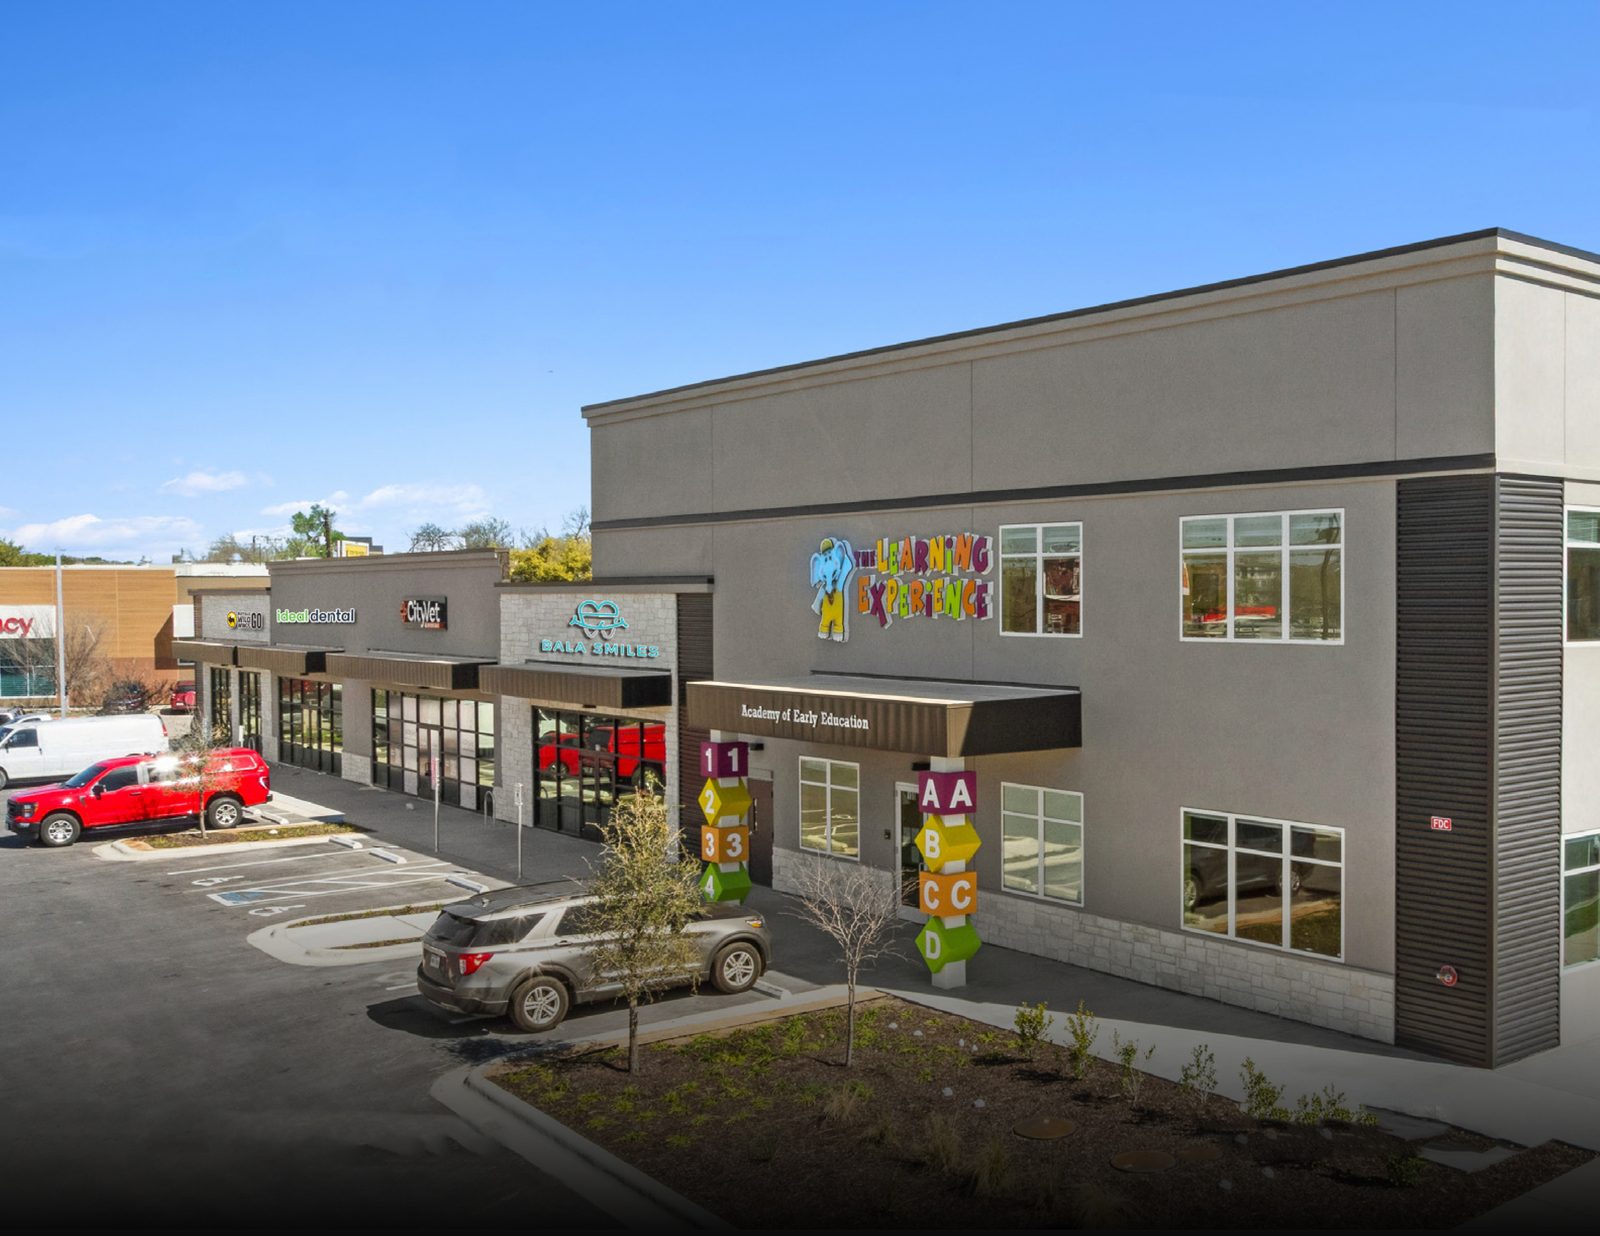
We are not buying a corporate covenant. We are buying irreplaceable frontage on the exact corridors where the neighborhood already shops — on leases that remove operational friction by passing every cost through to the tenant — acquired from legacy owners who never priced it as institutional real estate.
We acquire small-bay, daily-needs retail centers under 100% triple-net leases across Sun Belt growth markets and high-barrier infill submarkets. Returns are underwritten to the intrinsic real estate and lease durability — not to a credit rating, and not to cap-rate compression — and are manufactured through lease-up, rent resets, and disciplined re-tenanting.
Irreplaceable Retail Corridors
Frontage on the dominant retail artery of a trade area — traffic counts, ingress/egress, and co-tenancy with necessity-based operators driving recurring cross-shopping. Catchment affluence is not our primary screen; instead, we mandate that a tenant’s occupancy cost ratio (OCR) be highly supportable by the households it serves.
Tenant-Mix Alignment, Not Credit Gatekeeping
We underwrite the rent roll against the households it serves, then each tenant’s unit-level economics. Credit is an attribute, not a gate: a roll may be entirely national credit with no anchor, or entirely cycle-resilient local operators — childcare, medical, veterinary, fitness, value retail, QSR. Concentration is measured at the rent line, not by logo.
Embedded Mark-to-Market
We target fragmented, non-institutional owners with vacancy and below-market rents — acquired on in-place NOI, underwritten to stabilized NOI, with exit cap rates equal to or wider than our going-in basis.
Proven Execution Across Cycles
Proven execution across the risk-return spectrum — realized alpha, not mark-to-market.
Capital Deployed Across the Risk-Return Spectrum
Opportunistic / BTR Development
$50M Exited/Recapped · $120M Active
Value-Add / SFR Acquisition
$38.5M Exited · $10M Active
Land Development
Fully Realized
Special Situations
Fully Realized (1 Month Exit)